
Pros and cons
Pros
- Earns Marriott Bonvoy points on every spend — redeemable for free nights at 8,000+ Marriott properties globally
- Welcome benefit typically includes a Marriott free night award
- Travel category earns accelerated Bonvoy points
- Complimentary Marriott Bonvoy Silver Elite status on joining
Cons
- Value entirely dependent on Marriott hotel usage — no cashback or airline miles flexibility
- Bonvoy points earn rate on non-travel spends is modest
- ₹3,000 annual fee with no spend-based waiver
- Each Free Night Award expires 12 months from issue and cannot be transferred or gifted
- Fuel, rent, government payments, wallet and gift-card loads and online gaming earn nothing
- Grocery stops earning above ₹1.5 lakh of spend a month
India has surprisingly few hotel co-branded credit cards, and the Marriott Bonvoy HDFC is the country's only Marriott card — the default choice for anyone loyal to the world's largest hotel group. It's also one of the most honest cards on the market about what it is: a specialist. The everyday earn is thin, but almost the entire value rests on one benefit — the annual Free Night Award — and in 2026 that benefit got better. I've held this card for years, so this is a long-term holder's take, not a spec sheet.
The whole case in one line: the Free Night Award
The card gives you a Free Night Award worth up to 15,000 Marriott Bonvoy points as both a welcome benefit and a renewal benefit. On a ₹3,000-fee card (about ₹3,540 with GST), that single certificate is the entire argument: a 15,000-point night at a decent property comfortably clears the fee, often by a wide margin.
This is why I push back on the old "only worth it if you're a heavy Marriott guest" advice. The renewal night alone out-values the fee, so the real bar is much lower: will you spend even one night at a Marriott this year? If yes, the card pays for itself. And if you've never tried a luxury 5-star stay, this is the cheapest gateway into one I know of.
The real bar isn't a stack of nights a year — it's one. Spend a single night at a Marriott and the card has already paid for itself.
And in March 2026 the certificate got materially more useful: Marriott raised the Free Night Award top-up limit from 15,000 to 25,000 points. You can now add up to 25,000 of your own points to a certificate, lifting the realistic redemption ceiling to hotels priced around 40,000 points a night — from "good for a mid-tier property" to "good for a genuinely nice one." (The top-up points come out of your own balance, so it isn't free — but it dramatically widens where the certificate works.)
Everything you get: the benefits and memberships
This is not a thin card — the value is structured around recurring memberships and certificates that land every year, not a one-time sign-up sweetener. Per HDFC's own benefit listing, the package is:
- Free Night Award (up to 15,000 points) — as a welcome benefit and on every renewal.
- Complimentary Marriott Bonvoy Silver Elite status — a membership tier handed to you, not earned.
- 10 Elite Night Credits every year — a recurring head start toward higher Marriott status.
- Milestone Free Night Awards at ₹6 lakh, ₹9 lakh and ₹15 lakh of annual spend — up to three more free
nights a year on top of the renewal certificate.
- Earn rates of 8 Bonvoy points per ₹150 at Marriott, 4 on travel, dining and entertainment, and 2 on
everything else.
- Airport lounge access — 12 domestic and 12 international visits a year.
- Golf program — 2 complimentary games plus 2 lessons per quarter.
- 24/7 concierge.
A natural companion to your Amex points
If you already collect American Express Membership Rewards and transfer them to Marriott Bonvoy, this card is the perfect partner. The co-brand supplies the status, the certificates and the milestone nights; your Amex transfers top up the points balance you actually redeem with. Together they make the Marriott ecosystem far more powerful than either piece alone — which is exactly how I run mine.
The catch: weak everyday earning
As a general-spend card, this is poor, and I'll be blunt about the math. The base earn is 2 points per ₹150 — about 1.3% in points, and under 1% in real money, because each Bonvoy point is worth only ~60 paise on hotel redemptions. By comparison, a lifetime-free card such as the Amazon Pay ICICI returns 1% in plain cash on most everyday spend, and category cards pay far more in their niches. So I almost never swipe this card day-to-day; I hold it purely for the joining and renewal perks.
It also earns nothing on several common categories — fuel, rent, SmartEMI and Dial-an-EMI conversions, wallet loads, gift vouchers and government payments (HDFC doesn't say plainly whether a merchant EMI earns) — and it's on the Diners Club network, so keep a Visa or Mastercard for the offline gaps.
Turning a ₹6 lakh government bill into a free night
Here's a use case I stumbled into. I recently had to make a ₹6 lakh government payment through an official portal. Almost no Indian card earns rewards on government spends anymore (only some Amex variants), and Amex wasn't accepted on that portal anyway. So I put it on this card. It earned no base points — but it still counted toward the ₹6 lakh milestone and triggered an extra Free Night Award. If you have a large, unavoidable payment to make, routing it here can quietly convert a "dead" transaction into a free night. (Milestone qualification and base-point exclusions are tracked separately, which is what makes this work — though, as always with these cards, the rules can change without notice.)
What my 2-night Jaipur redemption actually cost
Used well, the points are genuinely rewarding. On a recent family trip — my wife, our two-year-old and me — I booked a two-night stay at the Fairfield by Marriott, Jaipur (26–28 January 2026). One night came free from the Welcome Free Night Award certificate; the second night was a standard award at 13,000 points. Here is exactly what those two nights cost me:
| My 2-night family stay — Fairfield by Marriott, Jaipur | What it cost |
|---|---|
| Night 1 — Welcome Free Night Award certificate | 0 points |
| Night 2 — standard award redemption | 13,000 points |
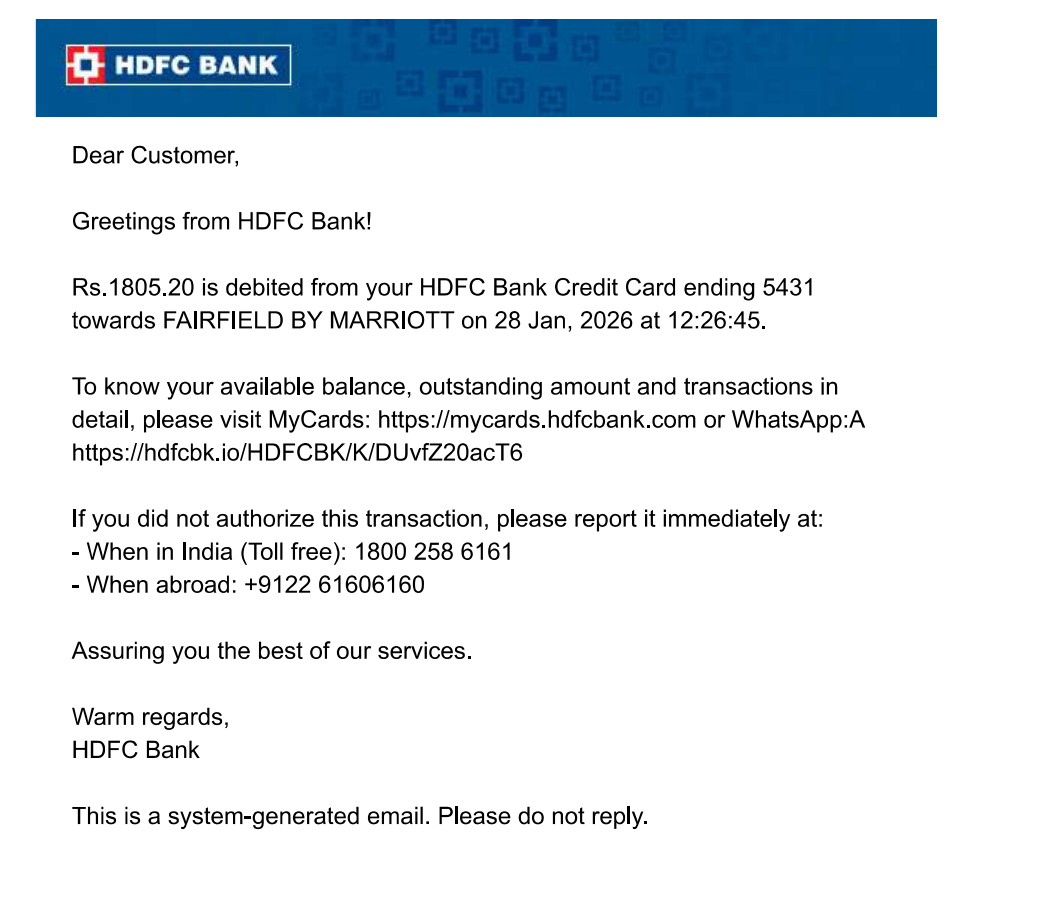
| Breakfast — whole family, already 50% off via Gold status (on the HDFC card) | ₹1,805 |
| Total cash out of pocket for two nights | ₹1,805 |
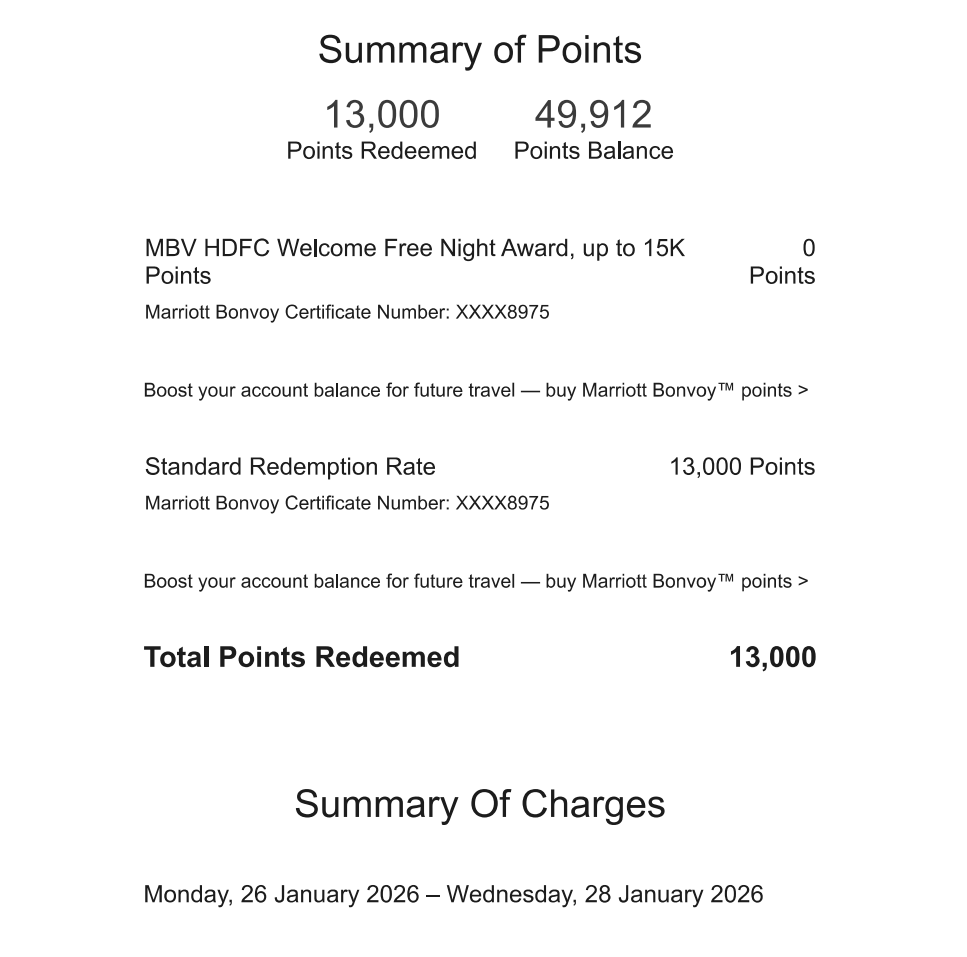
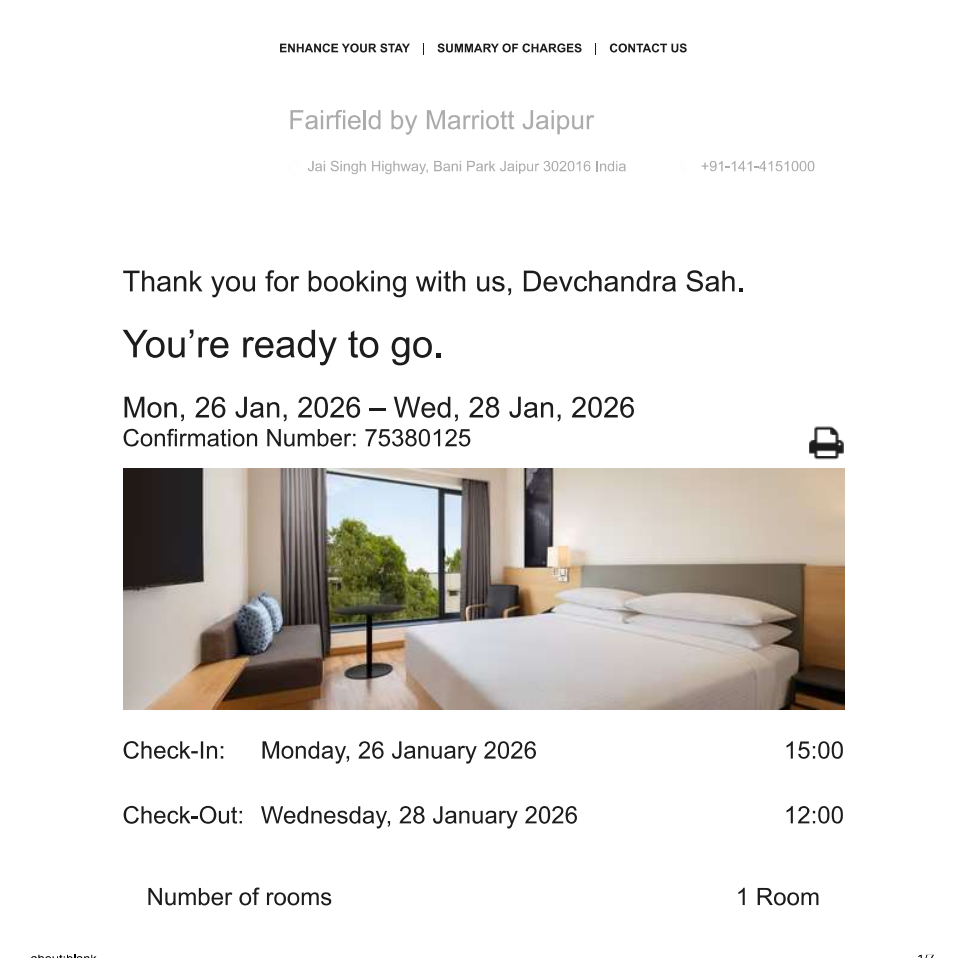
Two nights at a Marriott for 13,000 points and one half-price family breakfast — value the everyday earn rate would never suggest the card is capable of.
There is one thing to remember on award stays: breakfast is not officially complimentary when you book a room with points, unless you hold top-tier (Platinum and above) Marriott elite status. In practice it's handled case-by-case — a polite request at the front desk or the support line often gets Gold members a discount, and sometimes a comp, but it's request-based and never guaranteed. I was travelling with my wife and our two-year-old: as a Gold member it wasn't free, but a quick ask plus this card got me 50% off, so that ₹1,805.20 was the already-halved bill for the whole family across the stay — the only thing I paid for. Don't bank on the free buffet you'd get on a paid premium rate; budget for breakfast, then ask at the desk and you'll often pay less.
Who should hold it
The Marriott Bonvoy HDFC is built for anyone who'll spend even a single night at a Marriott this year, anyone who wants an affordable taste of a 5-star stay, and anyone who already funnels Amex points into Bonvoy. For them the renewal certificate, Silver status and 10 Elite Night Credits deliver real, repeatable value that dwarfs the ₹3,000 fee — and a high spender hitting the milestones earns multiple free nights and does even better.
It's the wrong card for anyone who never stays at Marriott, anyone hoping to use it as a daily driver (the earn is too thin), and anyone uncomfortable holding a card whose value depends on a hotel currency that can be devalued.
Should you get it?
The Marriott Bonvoy HDFC is a specialist that excels at its specialty. Judge it as an everyday card and it's mediocre; judge it as a Marriott loyalty tool and it's excellent — an annual Free Night Award that pays for the card off a single stay, made meaningfully better in 2026 by the top-up limit rising to 25,000 points. Add Silver status, Elite Night Credits and the Amex synergy, and for anyone with even occasional Marriott plans it's an easy yes. A one-trick card — but the trick is genuinely good, and it just got better. And for how Bonvoy points translate to value across every Indian transfer route, the programme page tracks the live ratios.
Decided the Marriott Bonvoy HDFC Bank Credit Card fits how you spend?
Applications are submitted to and decided by HDFC Bank. CardAdvisor does not issue cards or process applications.

I have spent over a decade on Indian credit cards, mostly for the points and miles. I am a software engineer by profession, I hold and use the cards I write about, and I redeem through airline and hotel transfer partners: Avios, KrisFlyer, Flying Blue, Air India Maharaja Club, Accor ALL, Marriott Bonvoy and Taj. What I write about is what a card is actually worth after the fine print, the caps and exclusions that decide the real return, and the changes issuers make quietly. No paid placements.
Frequently asked questions
Is the Marriott Bonvoy HDFC card worth it in 2026?
What is the Free Night Award on the Marriott Bonvoy HDFC card?
What status and memberships does the Marriott Bonvoy HDFC card give?
Is the Marriott Bonvoy HDFC card good for everyday spending?
Do you get free breakfast on points bookings?
How do you earn extra free nights on the Marriott Bonvoy HDFC card?
More guides
Researched from primary sources. How we review →
Independence. CardAdvisor is an independent editorial publication. We are not affiliated with, endorsed by, sponsored by, or authorised to act for HDFC Bank and American Express. All issuer names, product names, and payment-network marks are the property of their respective owners and appear here for identification and comparison only. Card faces shown on this site are our own original illustrations — we do not display or host issuer card artwork or logos.